10-year minus 3-month
+78 bpThe 10-year yield is 78 basis points above the 3-month yield.
US bond market dashboard
Each point shows the annual yield investors require to lend to the US government for a different length of time. Compare today's curve with earlier dates, then see which part of the market moved and why that matters.
Current curve and earlier markets
Compare today's official Treasury curve with earlier markets. The shape shows the cost of borrowing at each maturity; the historical lines show how that cost has changed.
What the curve is saying
The yield curve is not a forecast in its own right. Its shape shows how the market prices short and long lending periods; the useful information lies in which maturities moved, by how much, and what the rest of the economy was doing at the time.
10-year minus 3-month
+78 bpThe 10-year yield is 78 basis points above the 3-month yield.
10-year minus 2-year
+31 bpThis spread compares the market's medium-term policy sensitivity with longer borrowing costs.
Largest yield change over the past month
3-yearThe 3-year yield fell 22 basis points between September 23, 2026 and October 23, 2026.
Lending for three months is a different commitment from lending for ten years. Short yields closely follow expectations for Federal Reserve policy. Longer yields also reflect inflation, growth, Treasury supply and the extra compensation investors require for uncertainty.
The useful question: is the move concentrated in near-term policy, or in the cost of lending for longer?
An upward-sloping curve puts longer yields above shorter ones. An inverted curve does the opposite. But a steeper curve can come from falling short yields or rising long yields. Those changes carry different messages about policy and financial conditions.
The useful question: which end moved? A steeper curve alone does not tell you the economy is improving.
A single curve tells you where yields sit. Earlier curves tell you how they got there. Comparing the same maturities across dates helps distinguish a new move from a reversal or a repricing that has been building for months.
The useful question: is this a one-day adjustment or part of a sustained change in borrowing costs?
Higher yields can accompany resilient growth, persistent inflation or a rising cost of financing government debt. Inflation data, labor conditions, credit spreads and volatility help you judge which explanation has support. Similar curves can belong to very different economies.
The useful question: do the other signals support the bond market's message, or challenge it?
Why the curve matters
Treasury yields provide a common reference point for mortgages, company borrowing, equity valuations and the dollar. Their movement can tighten or loosen financial conditions before official economic data catches up.
Falling long yields can reflect weaker growth expectations, easier policy expectations, or both. Rising yields can accompany stronger activity, but they can also restrain demand as borrowing costs increase.
Inflation expectations influence longer yields. The cleaner read comes from comparing nominal yields with inflation compensation and real yields, rather than assigning every move to inflation.
A yield move means more when credit spreads, equities and volatility confirm it. MacroPulse uses those markets to distinguish orderly repricing from broader financial stress.
From the curve to the macro picture
A market regime describes the mix of growth, inflation and financial conditions. Similar yield curves can accompany very different economies. MacroPulse distinguishes these six settings by checking rates against activity, labour, inflation and credit.
| Regime | Growth | Inflation | What distinguishes it |
|---|---|---|---|
| Benign Disinflation | Cooling, without a sharp downturn | Easing | Inflation relief makes conditions less restrictive. Labour and credit still need to hold up. |
| Opportunity After Repricing | Mixed, but still holding | Lower, but not settled | Repricing has improved the compensation for taking risk. It has not removed the underlying fragility. |
| Restrictive Slowdown | Softening | May be easing | Tight policy is suppressing demand. Markets may be anticipating relief before the economy has stabilised. |
| Stagflationary Fragility | Slowing | Sticky | Weakening growth meets persistent inflation and pressure on longer-term borrowing costs, limiting room for policy relief. |
| Policy Rescue Transition | Weakening enough to need support | Less dominant, not necessarily resolved | Markets price policy relief because activity is deteriorating. Falling short-term yields can therefore be a warning. |
| Reflation with Doubt | Expectations improving | Unresolved | Growth optimism returns while inflation risk and longer-term borrowing costs continue to constrain the outlook. |
These descriptions explain the categories, not today's call. The Advanced workspace shows the current assessment, its confidence and the evidence that could change it. Regimes describe market conditions; they do not prescribe a portfolio.
Inside MacroPulse Advanced
MacroPulse checks the curve against inflation, credit, market stress and geopolitical risk, then publishes a dated view of the regime and the evidence that could overturn it. Historical asset behaviour provides context for your own decisions; it does not prescribe a portfolio. These screens are example captures from the Advanced workspace; the dated assessments inside the product update separately.
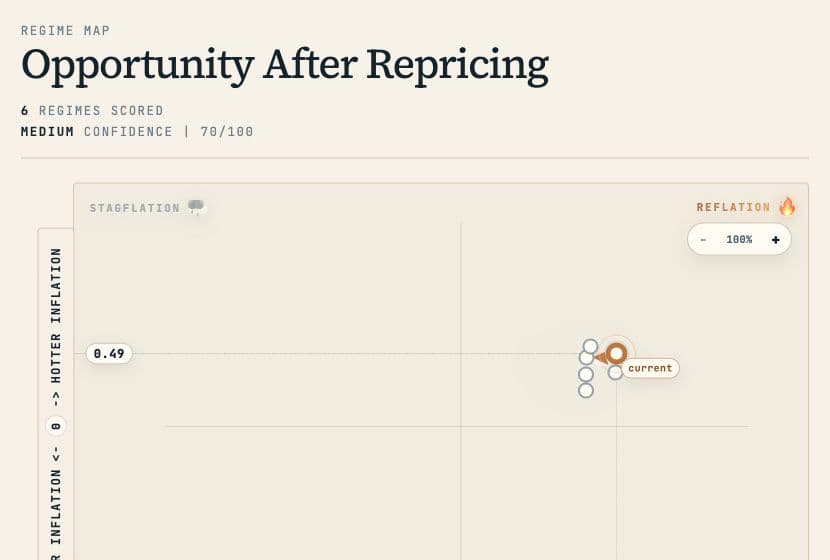
Locate today’s growth and inflation pressure, then see the nearest competing regime.
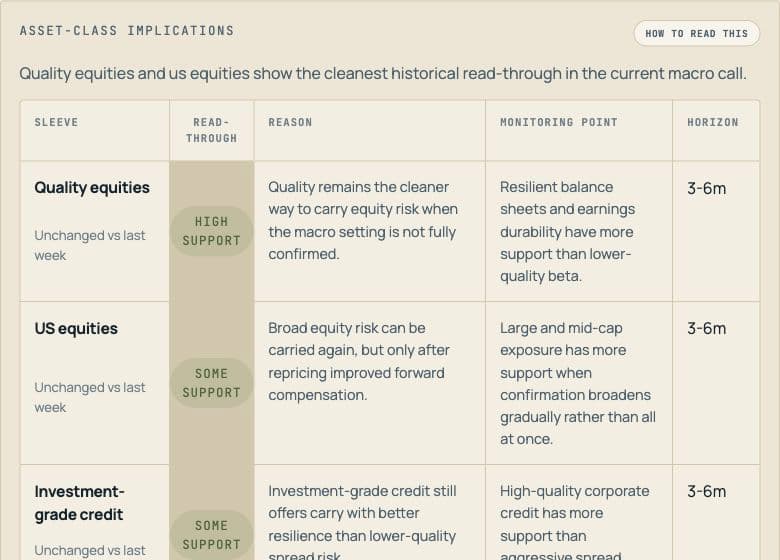
Compare how asset classes behaved in similar market settings. Context for your judgement, not a prescribed portfolio.
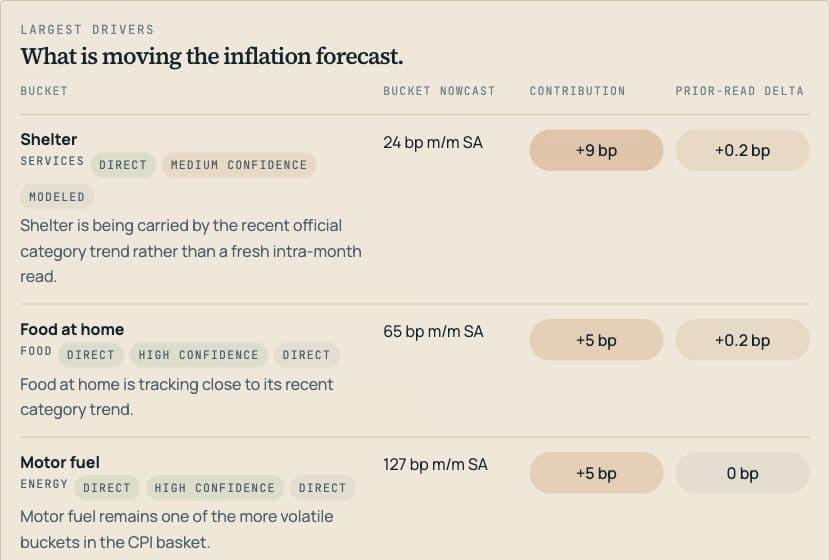
Track which CPI components are moving the nowcast before the official release.
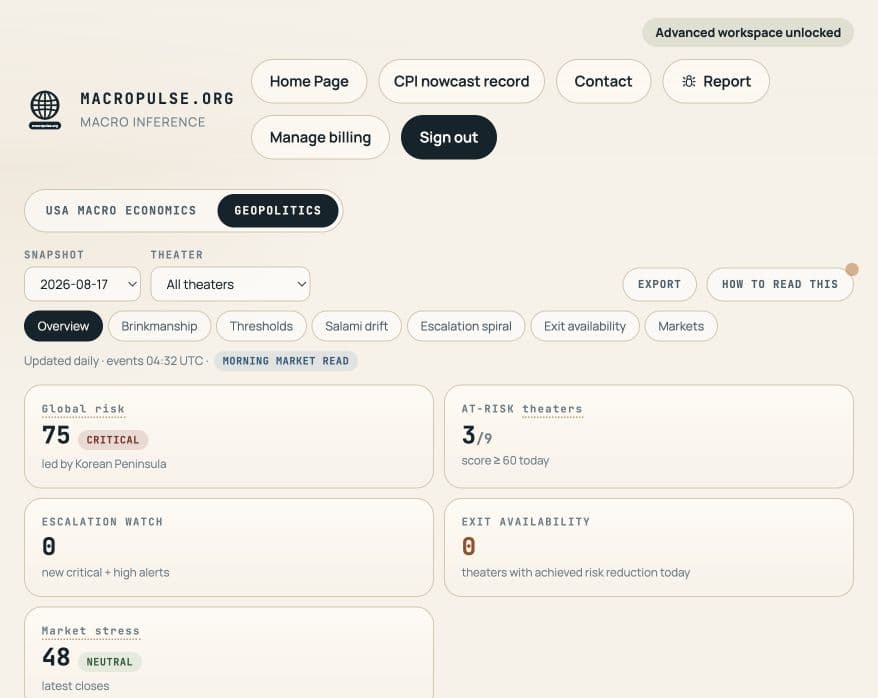
See which conflict theatres matter today and whether markets confirm the pressure.
Read today's regime, allocation view and supporting evidence.
$25/month USD · Cancel anytime · Plus applicable taxesTreasury yield curve questions
The curve is useful because it compresses many market judgements into one shape. These answers explain what it can tell you, and where its limits begin.
Each point is the annualised yield for lending to the US government over a particular maturity, from a few weeks to 30 years. Reading the points together shows how borrowing costs change across time.
An inverted curve has short yields above long yields. It can reflect tight policy and expectations of slower growth or lower future rates, but it is not a timetable or a stand-alone recession forecast.
Longer yields respond to more than the current policy rate. Inflation expectations, real growth, Treasury supply and the compensation investors require for uncertainty can all move the long end independently.
Start with the curve's shape and recent changes, then compare them with inflation, labor, credit, equities and volatility. Confirmation from the wider market helps distinguish an orderly repricing from broader economic stress.
The dashboard updates on US Treasury trading days. The latest observation shown here is October 23, 2026.
Every maturity
This table carries the same latest curve shown above in a format that can be read without the chart. Values are annualised yields.
Source: US Treasury yield curve methodology
Update cadence: Daily on US Treasury trading days.
Last data update: .
| Maturity | Yield (%) |
|---|---|
| 1-month | 4.11 |
| 6-week | 4.11 |
| 2-month | 4.16 |
| 3-month | 4.22 |
| 4-month | 4.30 |
| 6-month | 4.30 |
| 1-year | 4.44 |
| 2-year | 4.69 |
| 3-year | 4.75 |
| 5-year | 4.82 |
| 7-year | 4.89 |
| 10-year | 5.00 |
| 20-year | 5.37 |
| 30-year | 5.33 |
From understanding to following
You have seen how the curve works and why its changes matter. MacroPulse follows those changes alongside inflation, credit and geopolitical risk, with a dated assessment and the evidence behind it.
Research for your own judgement. No personalised investment recommendations.